The M2 widening proposal can be viewed here:
http://www.hillsm2upgrade.com.au/ea_documents.htm
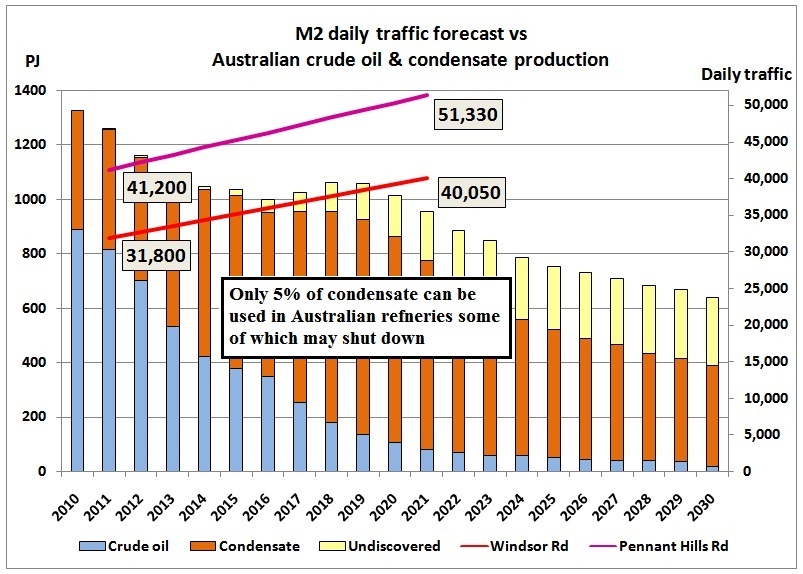
We superimpose traffic forecasts from chapter 7.2.3 on page 72 with crude oil and condensate projections of Geoscience Australia
Source of data:
https://www.ga.gov.au/image_cache/GA17051.pdf
It can be clearly seen that a huge gap between assumed traffic growth and declining oil production emerges already in the next years, just when the additional lanes are supposed to open for traffic. Please note that only 5% of the condensate can be processed in Australian refineries, some of which may have to close. So most of the condensate will be exported into the bottomless pit of the global oil markets.
The Federal Government is very well aware of the problem:
Supply fears as oil surges
21/2/2008
MARTIN FERGUSON, RESOURCES MINISTER: Australia’s got a huge challenge. We’ve got huge problems on the trade front, but also importantly, a real problem in terms of energy security and our economic future by 2015.
http://www.abc.net.au/7.30/content/2007/s2169087.htm
That was in February 2008. Are M2 planners not watching the 7.30 report? Why was so much work put into the M2 widening documentation?
What will replace oil? Not much. Read here:
6/1/2010
Diminishing Returns of Fossil Fuel Energy Invested
http://www.crudeoilpeak.com/?p=909
Here is the summary of my submission:
Contents:
Introduction: our energy dilemma
Summary
- M2 solutions
- Traffic forecasts vs. Australian crude oil porduction
- Failed tollway projects
- Timetable 2010-2020
- War games in the ME
- Flawed Metropolitan Strategy
- Global warming update
- Replacing coal until 2030
- Nuclear
- Solar and wind
- Potential energy for EVs (off-peak)
- Transitioning the car fleet
- Removal of bus ramp at Beecroft Rd
- Epping Heights Public – noise
Appendix on peak oil
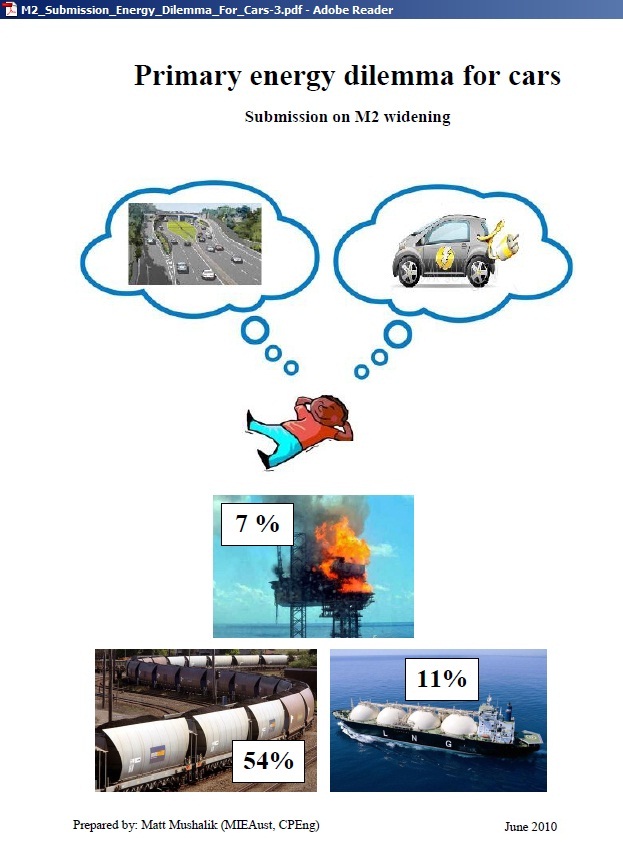
The above percentages of Australian energy production have been taken from: “Energy in Australia 2009″
http://www.abareconomics.com/publications_html/energy/energy_09/auEnergy09.pdf
The remaining percentages are 26% for uranium and 2% for renewables.
Peak oil not understood
Peak oil started 5 years ago, in 2005, and hit an economy with a pre-condition of accumulated debt. The combined effect of high oil prices and the financial turmoil resulted in a demand destruction in OECD countries of 5 mb/d – oil which was immediately consumed by OPEC and Chindia. Without the debt crisis and a continuing world-wide economic boom we would have had either physical oil shortages and/or skyrocketing oil prices by now – both of which would also have ultimately killed the global economy.
No crisis awareness
The M2 widening proposal knows nothing about all this and seems to be blissfully unaware of the consequences of peak oil, while at the same time the need to reduce CO2 concentrations from the current 387 ppm to 350 ppm means we have to replace our coal fired power plants, and very soon. The financial crisis is the 3rd challenge. The Middle East is another source of conflict which may impact on oil supplies. These 4 problems together will merge to a major crisis in this coming decade and have the potential to morph into a multiple system failure, if not well managed. With present business-as-usual policy settings – of which the M2 widening is part – the probability of this happening is increasing by the month, especially as problem #5 is the denial mode by governments of the above.
Energy security not checked
The M2 upgrade documentation (Environmental Assessment) does not contain any numerical calculations of the primary energy (measured in GL of fuels, GJ of fossil fuels or TWh of renewable energy) needed to operate vehicles for the duration of 30 years, the period used for the benefit cost analysis. Neither has it assessed the likelihood of the physical availability of such energies nor the risks associated with supply shortages, whether domestic or international. The Federal Resource Minister has already warned the public in February 2008 that there will be an oil import challenge (=crisis) as soon as 2015, only 2-3 years into the project life time.
Insufficient Fuel Savings
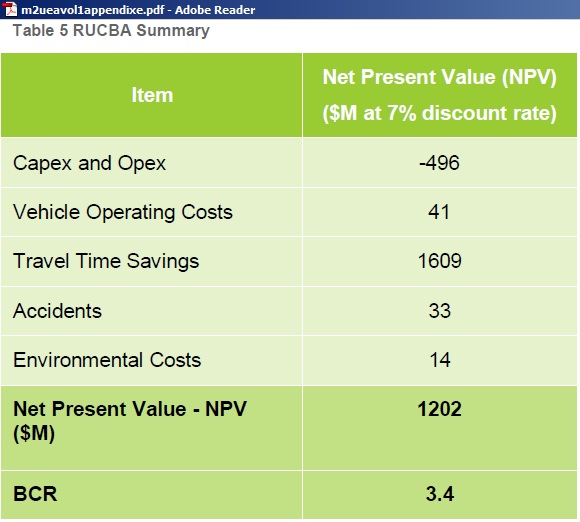
The Net Present Value calculation shows that vehicle operating cost savings are less than 10% of Capex and Opex. These vehicle operating costs would contain fuel costs as a major cost factor. From the point of view of reducing oil consumption and oil dependency this project is definitely not worthwhile.
Moreover, most of the time savings would be savings for private commuters, savings which would not translate into actual cash savings for the economy. Only commercial traffic would accrue these direct benefits. Table 5 does not show these commercial time savings separately. Insofar the table is highly theoretical. However, this is a basic problem in the RUCBA methodology
Terms of reference incomplete
The Director General’s requirements do not explicitly prescribe the above mentioned energy calculations and assessments. However, the consultant should have included this in the chapter on sustainability. After all, a project is not sustainable if there is not sufficient carbon free primary energy available at reasonable cost to support the assumed traffic volumes. Recent financial failures of toll-way projects in Australian Capital cities, but also in the US, due to over-optimistic traffic projections should have prompted the consultant to adopt this prudent approach. The problem here is that consultants want detailed design jobs of the projects they are preparing an EA for. So quite naturally they would not recommend to stop a project.
Prudence of investors
Even more importantly, it would be in the commercial interest of the motorway operator and potential investors in the project (most likely super annuation funds) to make sure that the energy security of the M2 upgrade is checked. Similar to the self interest of consultants many investors are keen to get commissions rather than to design a project which can be successful under all adverse conditions.
Duty of care of the Government
Moreover, the State government is and will be responsible for the overall functionality of the Sydney Metropolitan area in oil crisis years. It is very short-sighted, if not irresponsible, for the NSW government to argue that no taxpayer’s money is at risk. If investor money is lost, as experienced in the Global Financial Crisis, this impacts negatively not only on share holders or bond holders but also on the whole economy and ultimately on the State budget itself.
Oil supply risks in next years
There already is an oil supply risk in the next years. Oil shortages could result from an oil war or other armed conflicts in the Middle East as well as social unrest and oil hoarding when the truth comes out about OPEC’s overstated oil reserves, which have never been audited. Which company would actually make business with a partner whose books have never been audited? This is exactly what toll-way operators and investment funds are doing when they are spending funds on toll-ways.
Making business on the basis of oil imports from countries who don’t allow 3rd part oil reserve audits is fraught with incalculable risks. Given Australia’s 80% dependency on imported crude and fuels, and the lack of a Strategic Oil Reserve, the impact of such events will be felt within weeks. Petrol rationing and/or mandatory car pooling will mean reduced traffic and toll revenue. Depending on repayment conditions of project debt, the financial end of the M2 upgrade would follow soon.
Recommendation
The M2 upgrade documentation must be re-written to include an energy availability assessment. This analysis will show, as is already calculated in this submission, that the upgrade is neither commercially nor environmentally feasible and that it does not guarantee the long distance commuting by private vehicle which will become dysfunctional within 5-10 years, irrespective of the introduction of green cars, yellow cars or electric cars.. The 2nd focus of the review should therefore be a new chapter on alternatives to the 3rd lane. There are 2 options which should be investigated:
- Transperth model (electric rail Epping – Quakers Hill on the M2/M7 with a branch to the Norwest Business Park)
- Electric trolley buses because they can be rolled out faster than rail
Manufacturing capacity for trolleys should be built up IMMEDIATELY. These buses will be needed anyway in hilly areas of Sydney. The current bus fleet needs to be converted to CNG (compressed natural gas)
Full report , as PDF file ( 8 Mb): M2_Submission_Energy_Dilemma_For_Cars